
About this blog: I have been investing for 25 years, professionally and personally. I look for stocks that have a high probability of compounding at 15% for at least 5 years with limited downside. I write these stocks up on my blog. You can find more about me, my philosophy, my mental models, and my portfolio structure on my site.
Howard Hughes delivered significant news at its shareholder meeting yesterday. This note follows my review published in May and my valuation update a month ago.
My take is this is potentially very positive. I won’t redo my valuation until transactions are completed, but HHH is both accelerating the redeployment of capital into more highly-valued businesses and converting its real estate arm into a more capital-light and efficiently-funded operation.
Key takeaways
Howard Hughes are clearly getting more and more excited about the potential for Vantage, their recently-acquired insurer, under the guidance of Marc Grandisson, one of the industry’s titans.
They are also frustrated about the cost of capital investors apply to the legacy real estate operations, which they think is too high and which depresses the share price.
The obvious answer is to accelerate monetisation of real estate, and pump the capital into Vantage.
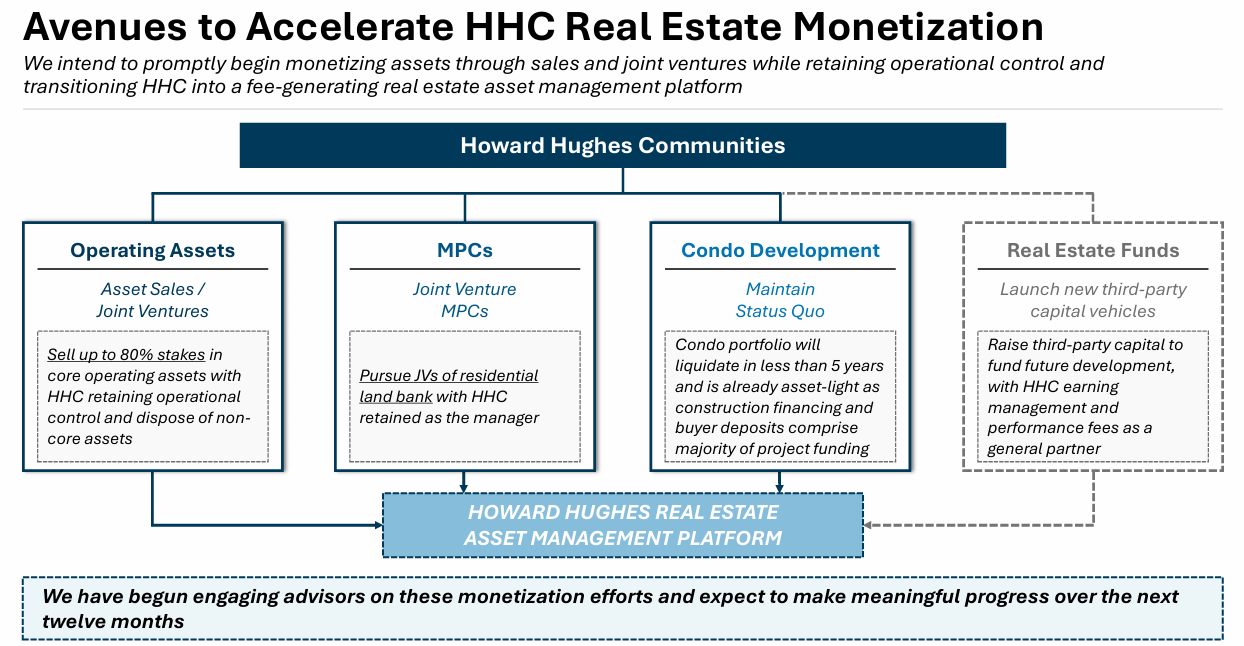
They think they can raise $3-4bn from real estate by year end 2027. c.$1.6bn of this comes from Operating Assets; this will be a relatively straightforward transaction. The remainder comes from the master planned communities. This will be trickier but this is a perfect asset for low cost of capital investors seeking long term real estate exposure through a capable, established manager.
Importantly, there is no plan to accelerate lot sales in the MPCs, which could damage value. However, they might raise third party capital to accelerate commercial and vertical development in the MPCs, which should enhance the value of the remaining land. These projects are currently not being done because insurance offers better returns.
Proforma for these transactions Howard Hughes Corp, the real estate subholdco, will have two parts: a capital light asset manager which should command a premium multiple, and a residual stake in the real estate assets mostly funded by existing debt.
The proceeds will be used to buy more of Vantage and to increase Vantage’s capitalisation, so that it can grow without excessive leverage. The short term effect is that real estate capital currently valued below NAV by the market will be moved to insurance, where is should be valued above NAV. The longer term effect is that more capital will be in the higher-return insurance arm, and the newly asset-light real estate arm should command a higher multiple.
Detailed notes
Vantage
Pershing have generally avoided banks and insurance companies in their portfolio; Vantage is different because they were able to do deep due diligence on the book and have control, so they can pick the team.
Purchase timing was lucky - sold the fixed income portfolio before rates spiked and bought equities at a low point.
It’s not a hard market but prices are still increasing in many markets and they are a small company. Plenty of opportunity to expand profitably. Vantage is small but broad - perfect for finding hard pricing pockets. Deep dive currently ongoing to find these.
Grandisson started at Berkshire under Ajit Jain and Pershing have been seducing him for a year and a half.
Have a lot of interest from people wanting to join Vantage under Marc; might lead to higher costs initially but the ROI on hiring great talent is very high.
With an (even) better team at Vantage they might be able to increase premiums/equity and raise ROE.
Ackman: insurance and investment are two businesses where the gap between tier 1 people and tier 2 people is 50-100x, not the 25-50% you normally see in business.
Vantage “does not have to generate a return by a certain quarter or growth rate by the end of the year…Pershing Square views [its] stake in the company as effectively a permanent one. Our goal is to compound the value over a very long period of time. The bulk of the profits from a well-run insurance company in this model will come from the asset side…so there really isn’t pressure on the insurance team to put capital at risk.”
Real estate - moving towards asset-light
Market applies a high discount rate to land ownership and real estate development. So “we’re going to do what most real estate investors do. We’re going to become a much more asset capital-light real estate investor by bringing in partners.”
Can raise $3-4bn by yearend 2027 as follows.
Operating assets: will monetise 80% of the $2.2bn of equity. “A pretty straightforward transaction.”
MPCs: will form JVs, with partners taking 80%. This is more difficult but it’s an ideal real estate asset for family office/pension, with a multi-decade deal pipeline and excellent management and development capability. There is no plan to accelerate lot sales, which could impair long term value.
Condos: already asset-light and self-liquidating so no change. However they might raise 3rd party funds to accelerate vertical development opportunities in the MPCs, which are currently not getting done because it’s better to deploy capital into insurance.
HHC, the real estate subsidiary, becomes much capital lighter:
Asset management, which is capital light and should command a high multiple.
Ownership of residual stakes, mostly funded by the existing debt at HHC which pays between 4.1% and 6.1% and matures between 2029 and 2034. As an aside, I could see the HHC bonds selling off on this news; a lot of equity is about to be taken out above them.
If the stock is so cheap do buybacks make sense? “Actually, in this case, I don’t think so. I think the highest return we can generate today is every marginal dollar of capital and put it into the insurance company”, where it goes from being valued at under book value to 1.5-2x, or buying more of Vantage by repaying the pref.
Buying other businesses to build a diversified holding company will follow once the insurance company is “very well capitalised” but is not a near to intermediate term priority.
Thanks for reading. If you have enjoyed this, please like and restack!
Pete
Disclaimer: This post is for informational and educational purposes only. Building Arks is not licensed or regulated to provide any financial advisory service and nothing published by Building Arks should be taken as a recommendation to buy or sell securities, relied upon as financial advice, or treated as individual investment advice designed to meet your personal financial needs. You are advised to discuss your personal investment needs and options with qualified financial advisers. Building Arks uses information sources believed to be reliable, but does not guarantee the accuracy of the information in this post. The opinions expressed in this post are those of the publisher and are subject to change without notice. The publisher may or may not hold positions in the securities discussed in this post and may purchase or sell such positions without notice.